What should buyers inspect on Discovery Bay Waterfront Properties?
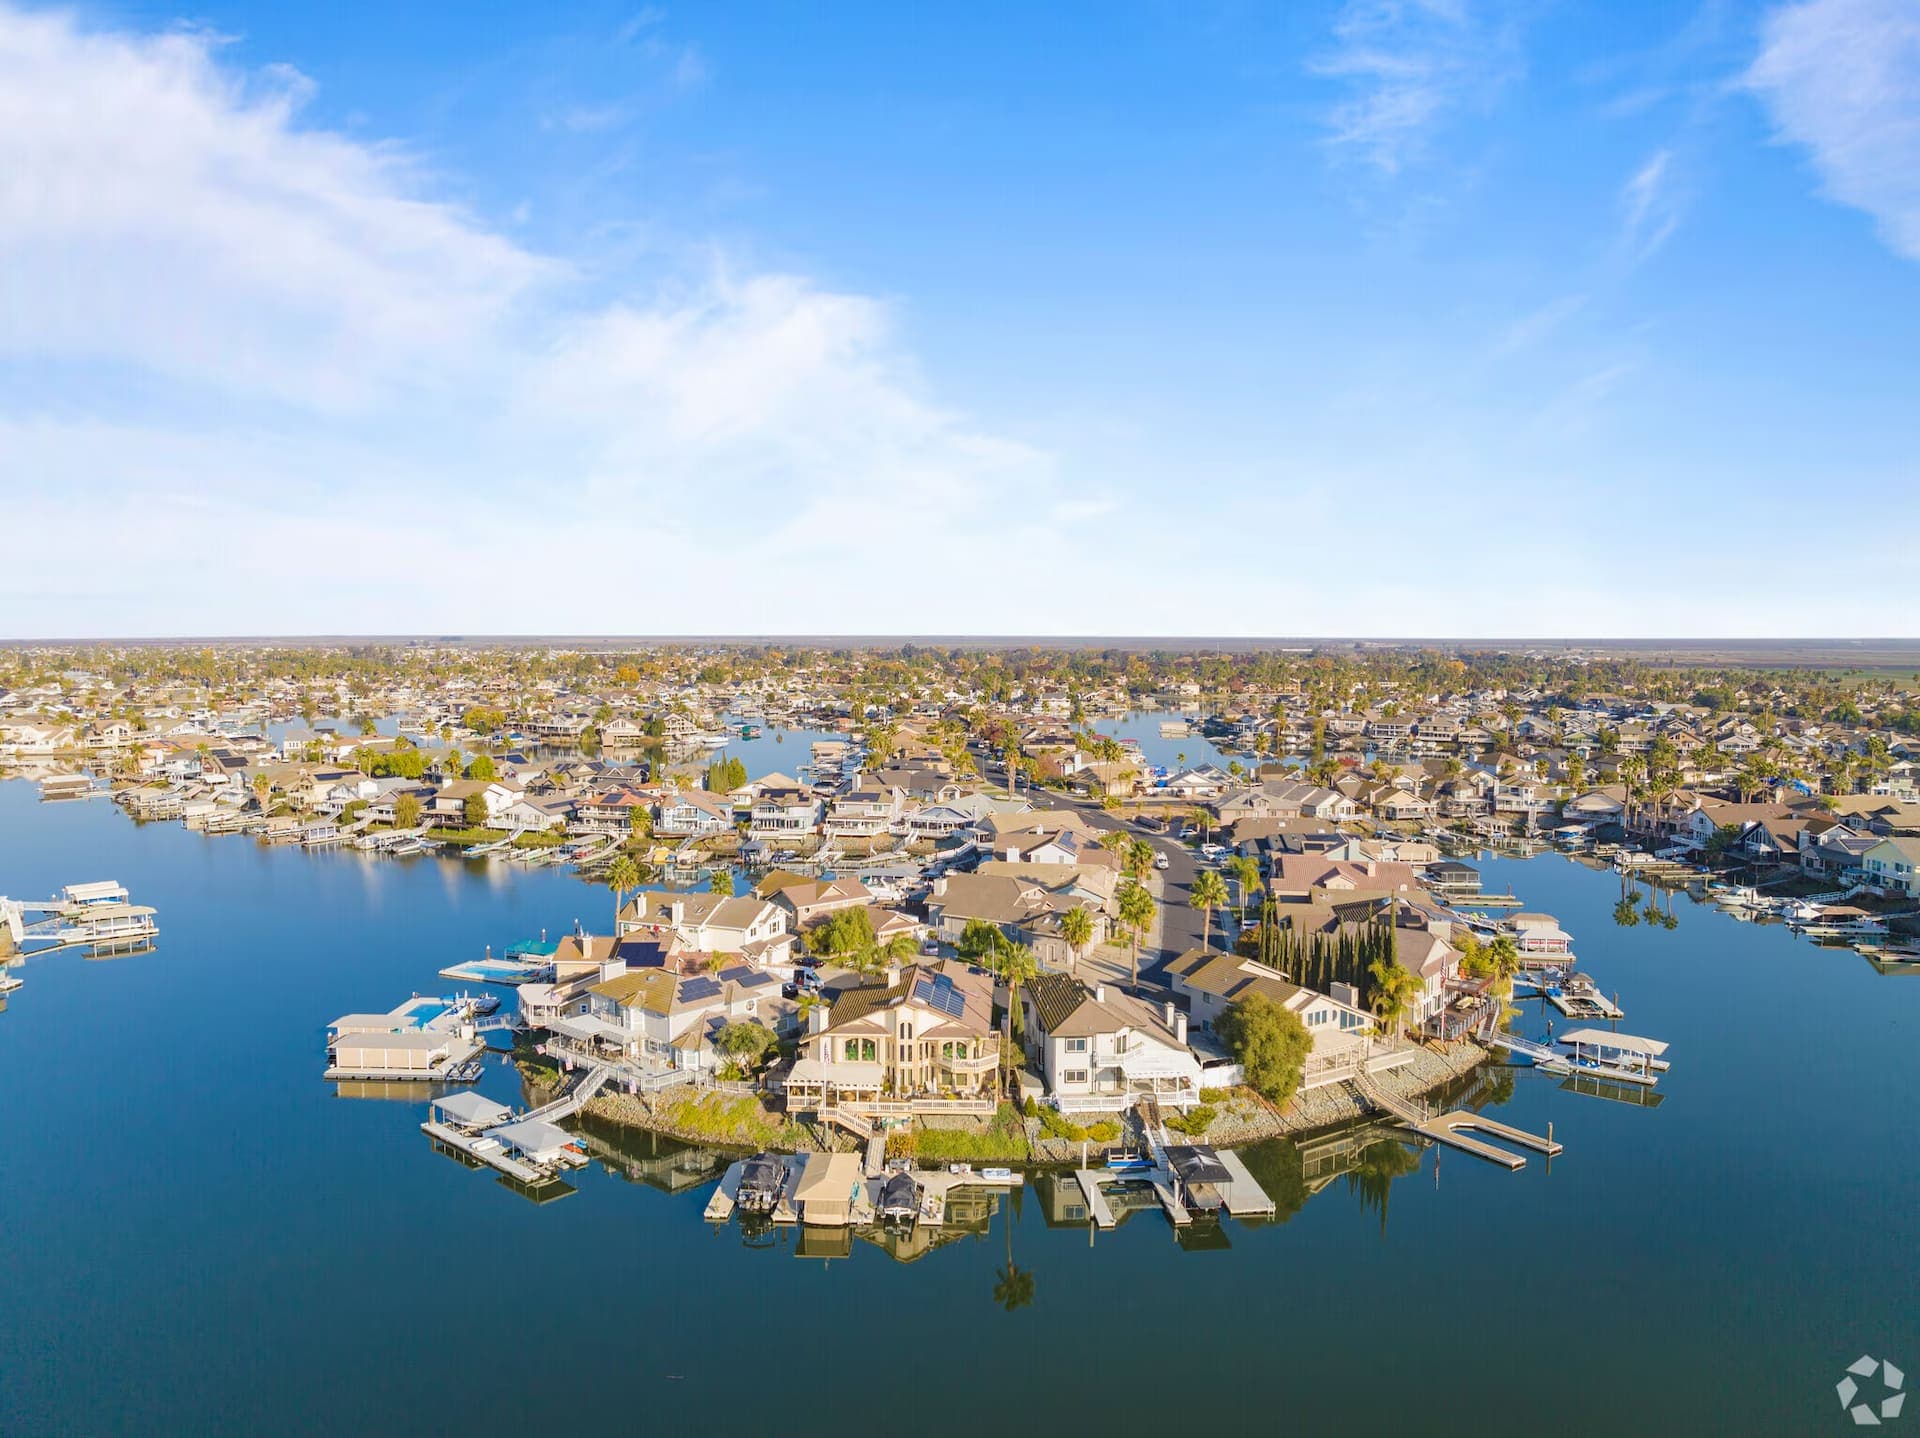
Buyers of Discovery Bay Waterfront Properties should inspect the dock, the seawall or shoreline slope, flood and insurance exposure, maintenance responsibility, and the boat route to open water, in addition to the house itself. A standard home inspection won't cover most of that. The dock and shoreline often call for a marine contractor or waterfront engineer, and the answers need to be in hand before you remove contingencies.
Key Takeaways
-
Recent local market data shows a median sale price of $745,000 in Discovery Bay across 71 homes sold in roughly the last 90 days, but that is an area-level figure and not a measure of any one waterfront home.
-
Reclamation District 800 maintains nearly 19 miles of levees protecting about 7,000 acres and roughly 3,600 properties, but that does not make the district responsible for your private dock or seawall.
-
Standard homeowners insurance does not cover flood damage, so get a flood-zone determination and written quotes before your inspection or financing period ends.
-
The dock and the shoreline structure should be inspected as two separate systems, each with its own records, permits, and repair history.
-
A Delta frontage premium or discount has to be judged against truly comparable properties, not a flat percentage.
How do you inspect a dock and seawall on Discovery Bay Waterfront Properties?
Treat the dock and the shoreline as two separate structural systems, and have each one evaluated by someone qualified to judge it. In my experience working with Delta-area buyers, the general home inspection ends at the back door, and that's exactly where the expensive questions begin.
What should an inspector check on the dock?
A dock is a structure sitting in moving water, and it ages differently than the house. The review should cover:
-
Pilings, including rot, cracking, loose connections, and signs of movement
-
Framing, decking, and fasteners, including corrosion and soft or failing boards
-
Flotation, gangways, and the connection from the dock to the shore
-
Cleats and tie-off hardware
-
Electrical equipment and anything running power or water to the berth
-
Boat lifts and covers, including their condition and rated capacity versus your vessel
If the inspector flags structural concerns, bring in a marine contractor before your contingency period expires. That's how you find out whether you're looking at routine upkeep or a major replacement.
How can you tell if a seawall or shoreline slope needs repair?
Look for movement and water getting where it shouldn't. Warning signs include:
-
Erosion, settlement, or undermining behind or beneath the structure
-
Cracking, displaced rock or concrete, or a leaning bulkhead
-
Exposed roots and drainage discharging over the bank
-
Differential movement between the house, patio, deck, and shoreline structure
When you see movement or instability, get an opinion from a qualified marine, geotechnical, or civil professional. A cosmetic crack and a failing bank can look similar to a buyer, and they are not the same problem.
Which records should you request before removing contingencies?
Existing construction is not proof that the work was approved. Ask for dock, lift, seawall, shoreline, and deck records, along with permits and final approvals, engineering reports, invoices, warranties, and prior-repair documentation. Also ask for any notices from Reclamation District 800 and any association approvals. If a record doesn't exist, that's not automatically a deal-breaker, but it's information you need before you commit.
For a wider look at the buying process on the water, see my Discovery Bay waterfront homes buyer guide.
Do Discovery Bay waterfront buyers need flood insurance, and who maintains the bank?
Yes, you should price flood insurance separately, because standard homeowners insurance does not cover flood damage. Contra Costa County's flood preparedness guidance advises homeowners in flood-prone areas to consider separate coverage, including policies available through the National Flood Insurance Program.
What should you ask for in writing on insurance?
Get a flood-zone determination and written quotes before your inspection or financing period expires, not after. Then ask each carrier about these items separately:
-
Building coverage and contents coverage
-
Personal liability
-
Dock or detached-structure coverage
-
Water backup
-
Erosion or earth-movement exclusions
-
Whether a boat lift or seawall is covered at all
Those exclusions are where surprises hide. A quote that covers the house but excludes the shoreline structure is a very different product than it looks like on the first page.
Does Reclamation District 800 maintain my dock or seawall?
Not automatically. Reclamation District 800 maintains nearly 19 miles of levees protecting approximately 7,000 acres in and around Discovery Bay, and it provides flood protection for about 3,600 properties. The district inspects those levees against state and federal standards for minimum 100-year flood protection.
That levee role does not establish responsibility for a private dock, seawall, bank, or slope. Local disclosure guidance, including the Contra Costa County Disclosures and Disclaimers Advisory, notes the district's role in maintaining waterways and channel slopes, and states that slope control and maintenance are generally the property owner's responsibility. Confirm the allocation for your specific parcel by reviewing title documents, recorded restrictions, subdivision materials, district information, and any maintenance agreements.
What ongoing costs come with Discovery Bay Waterfront Properties?
Expect a category of costs that inland homes don't carry. These include:
-
Dock and lift upkeep
-
Piling or flotation replacement
-
Decking and hardware
-
Shoreline or seawall repair
-
Bank vegetation control and drainage maintenance
-
Dredging or sediment-related work where applicable
-
Association assessments and district charges
-
Flood-insurance premiums
I won't hand you a generic dollar range, because it varies too much by property and I'd rather you get real numbers from contractors and insurers on the specific home. That's exactly the kind of question I walk buyers through before they write an offer.
Can your boat reach the Delta, and what does Delta frontage do to value?
Whether your boat reaches the Delta depends on the exact water setting of the property, and the premium for frontage depends on comparable homes, not a rule of thumb. Start by asking whether the lot fronts an interior lake, a canal, or a connection with practical access to the open Delta.
How do you verify boating practicality?
Request the actual route from the berth to where you intend to go, then evaluate it for your own vessel. Check bridge clearance, channel width, depth, current, tides, and obstructions against your boat's draft and height. The Town of Discovery Bay offers boating-safety information and links to a California Department of Boating and Waterways guide for Delta navigation, which is a useful starting point. For a feel for day-to-day use, I'd also read my post on boating in Discovery Bay.
Is a home with direct Delta access worth more?
Sometimes, but I won't quote you a flat percentage, because no generic number holds up. A property's value should be analyzed against comparable homes with similar water type, dock condition, navigability, lot orientation, bridge access, boat-lift capacity, seawall condition, and insurance or maintenance obligations. Two homes on the same street can price very differently on those factors alone.
For context on the broader market, here is how Discovery Bay sits among nearby East County areas. These are area-level medians, not a measure of waterfront value, and an individual home depends on condition, street, and timing.
Source: aggregated public listing data, trailing 90 days, as of October 2026.AreaMedian Sale PriceMedian Days on MarketDiscovery Bay$745,00041Antioch$572,50039Oakley$665,00042Pittsburg$557,50046Bethel Island$853,30845Bay Point$500,00040Clayton$1,128,00047 Recent local market data also shows 100 active listings in Discovery Bay, 26 new listings in the last 30 days, and 71 homes sold over roughly the last 90 days. Homes that sold had a median of 41 days on market. Those numbers tell you the market has options, which gives you room to be thorough with inspections rather than rushed.
If you're weighing the lifestyle side too, my waterfront living guide covers what daily life on the water involves.
FAQ
Does homeowners insurance cover flooding in Discovery Bay?
No, standard homeowners insurance does not cover flood damage. Contra Costa County advises homeowners in flood-prone areas to consider separate flood insurance, including coverage through the National Flood Insurance Program. Get written quotes and a flood-zone determination before your contingency period ends.
Who is responsible for maintaining the canal bank, slope, seawall, or levee?
It depends on the parcel, so confirm it in your documents. Reclamation District 800 maintains the levees, but local disclosure guidance states that slope control and maintenance are generally the property owner's responsibility. Review title documents, recorded restrictions, and any maintenance agreements rather than assuming the district covers a private seawall or bank.
Can my boat reach the Delta from a Discovery Bay dock?
It depends on the water the property sits on and your vessel. Ask whether the lot fronts an interior lake, a canal, or a route with practical Delta access, then check bridge clearance, channel depth, current, and obstructions against your boat's draft and height. Verify the route before you rely on any listing description.
What permits are required to repair or replace a Discovery Bay dock?
Requirements depend on the work and the waterway, so confirm them before you plan or price any repair. Ask the seller for existing permits and final approvals, and check with Reclamation District 800 and any association that may need to sign off. Existing construction is not proof it was approved.
Is a Discovery Bay waterfront home worth more with direct Delta access?
It can be, but the premium is property-specific. Compare homes with similar water type, dock condition, navigability, lot orientation, and seawall condition, and factor in insurance and maintenance obligations. A flat waterfront percentage will mislead you.
Ready to evaluate a specific home?
The core takeaway: Discovery Bay Waterfront Properties reward buyers who inspect the dock, shoreline, insurance, and boat route before they commit. If you're considering a home on the water, I'll help you build the right inspection team and compare it against real comparables. Schedule a consultation and we'll walk through the property together.
About The Best of East County Living
The Best of East County Living is operated by E3 Realty & Home Loans, a boutique Brentwood-based brokerage and mortgage broker that has helped over 1,000 families buy and sell across East and Central Contra Costa County since the mid-2010s. Built on Excellence, Energy, and Execution, the team pairs deep local expertise with in-house lending for a single point of contact from first conversation through closing.
E3 Realty & Loans · 925-603-3619
Equal Housing Opportunity. E3 Realty & Home Loans, CA DRE# 02073759, NMLS# 1770437, regulated by the California Department of Real Estate. This article is general information, not legal, tax, or financial advice; confirm your own numbers with your closing agent, tax advisor, or lender.
This article is general information only, not legal, tax, or financial advice. Verify all costs, tax obligations, market figures, and transaction specifics with your attorney, tax advisor, lender, or escrow officer before proceeding.